Projects / Master's coursework
Portfolio optimisation
Markowitz and asset selection for a Sharpe contest
Summary
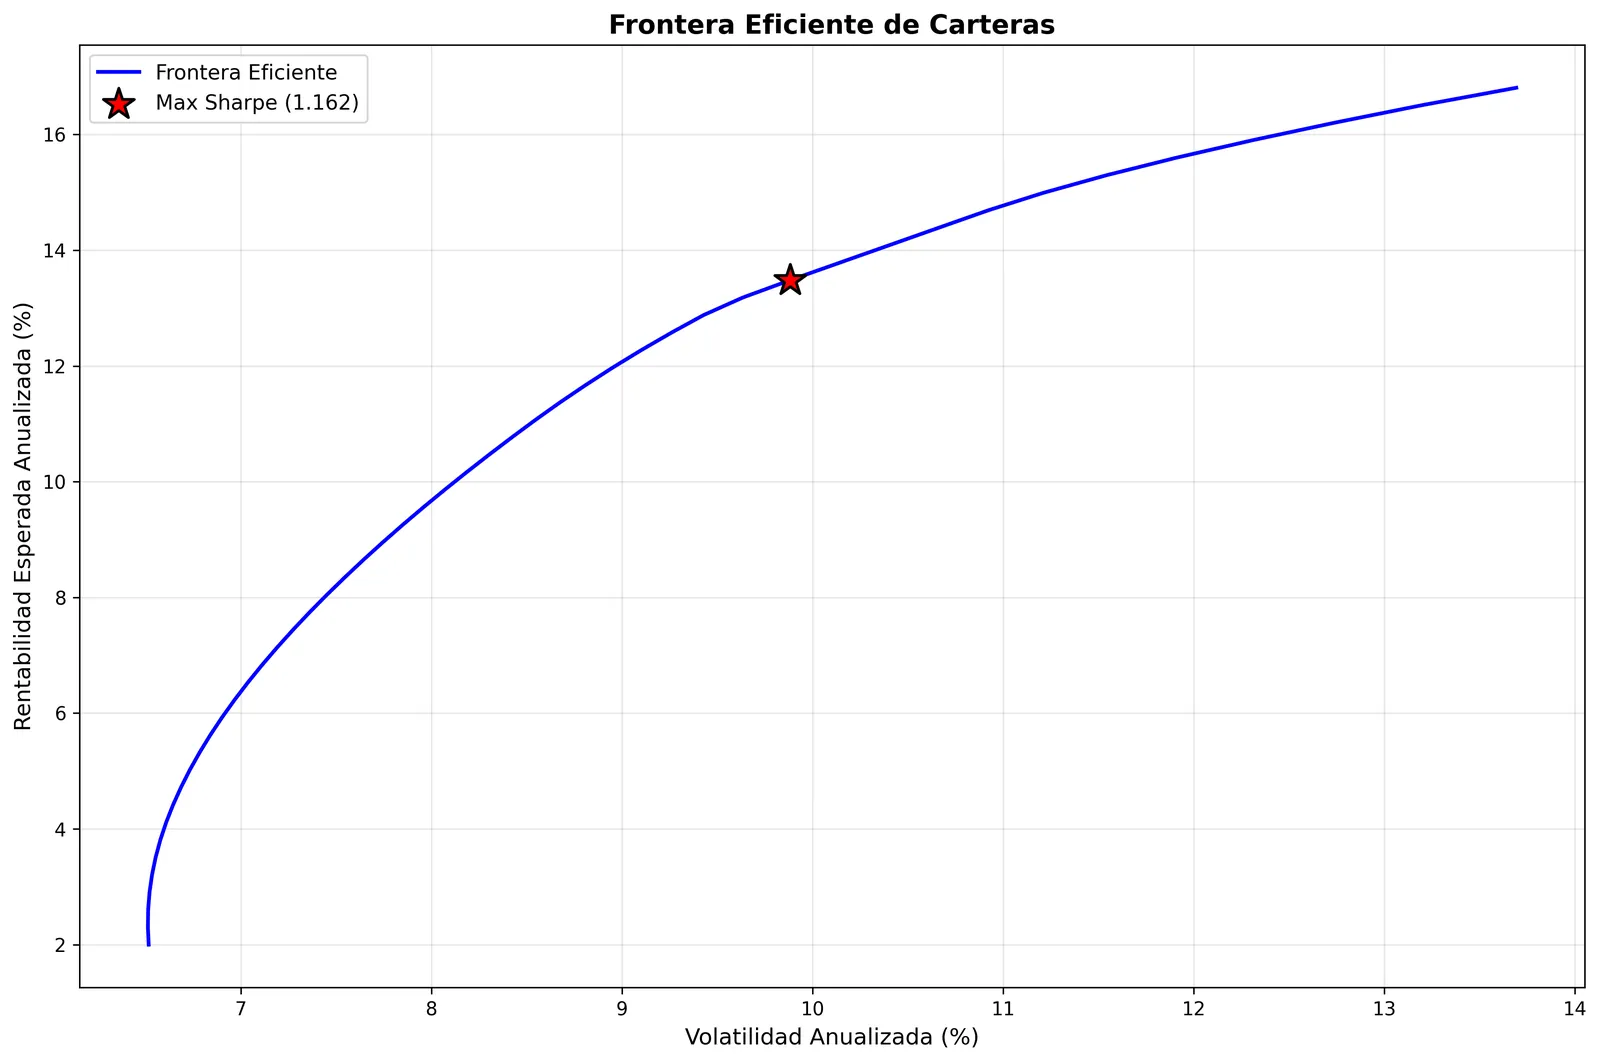
Diversification analysis, Markowitz optimisation and asset selection over 50 anonymised assets, for a class competition scored on annualised Sharpe ratio. The maximum-Sharpe portfolio reached 1.16 on the training data.
What it does
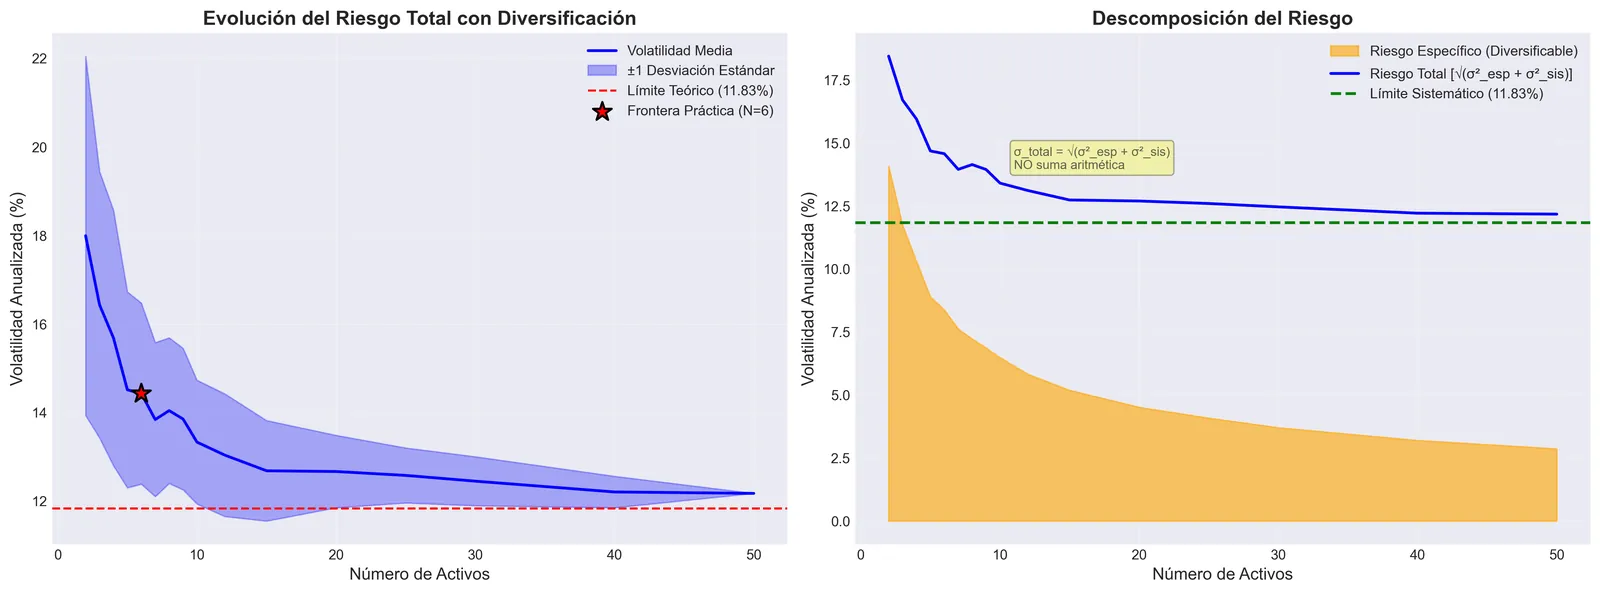
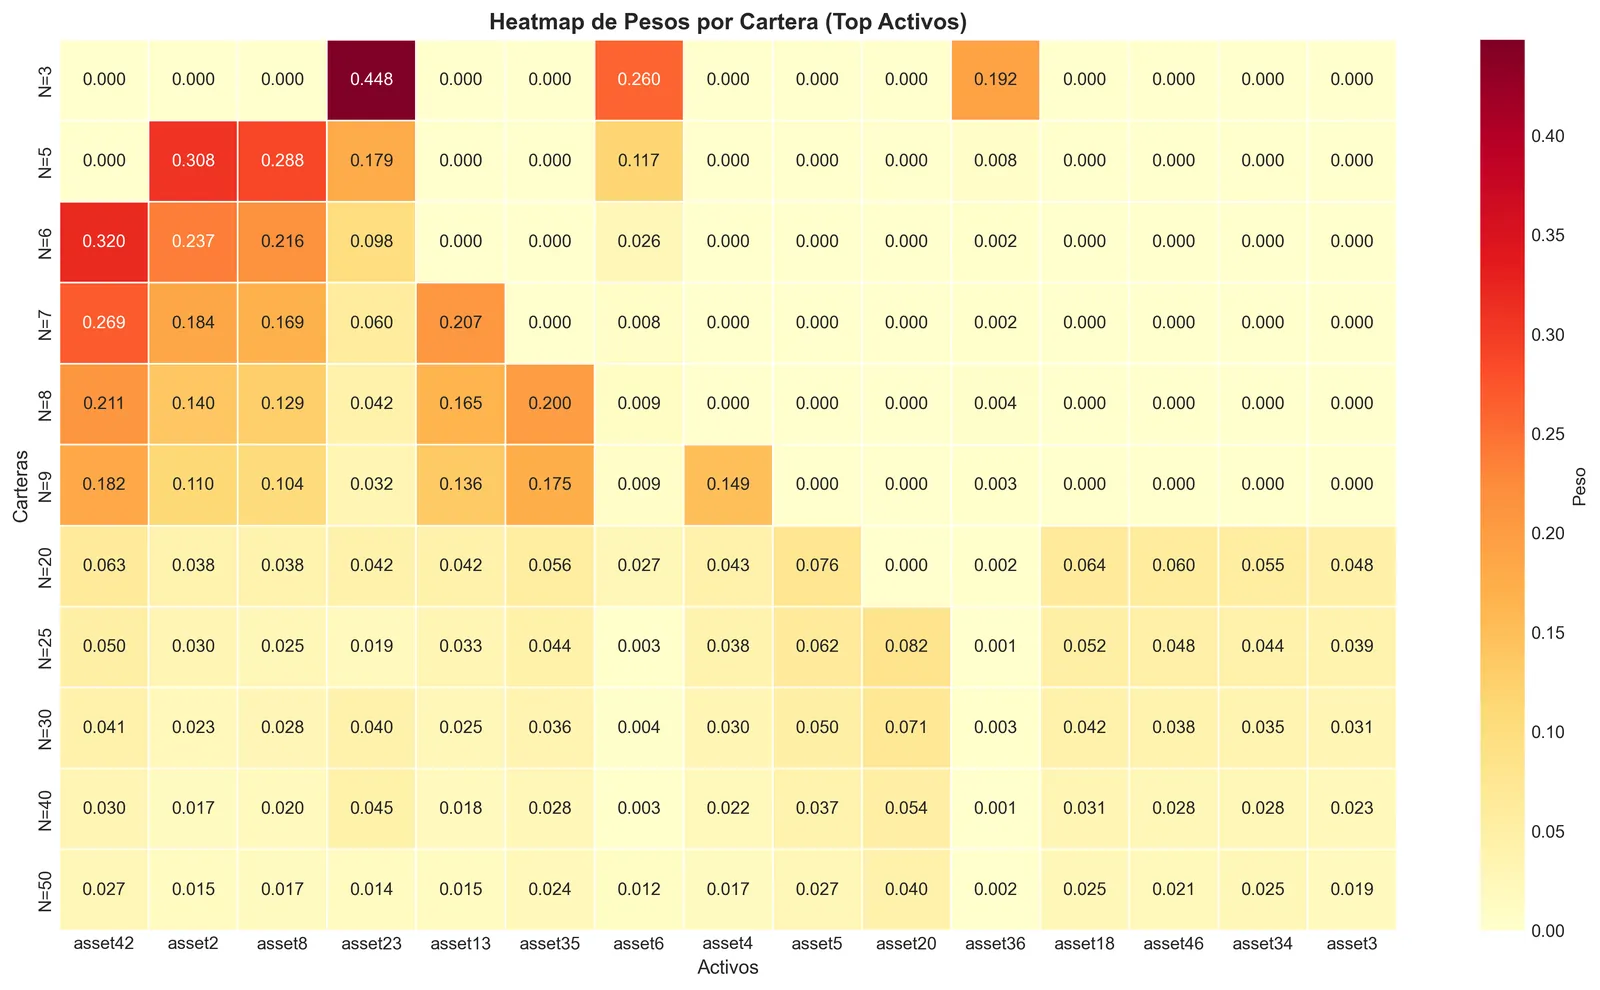
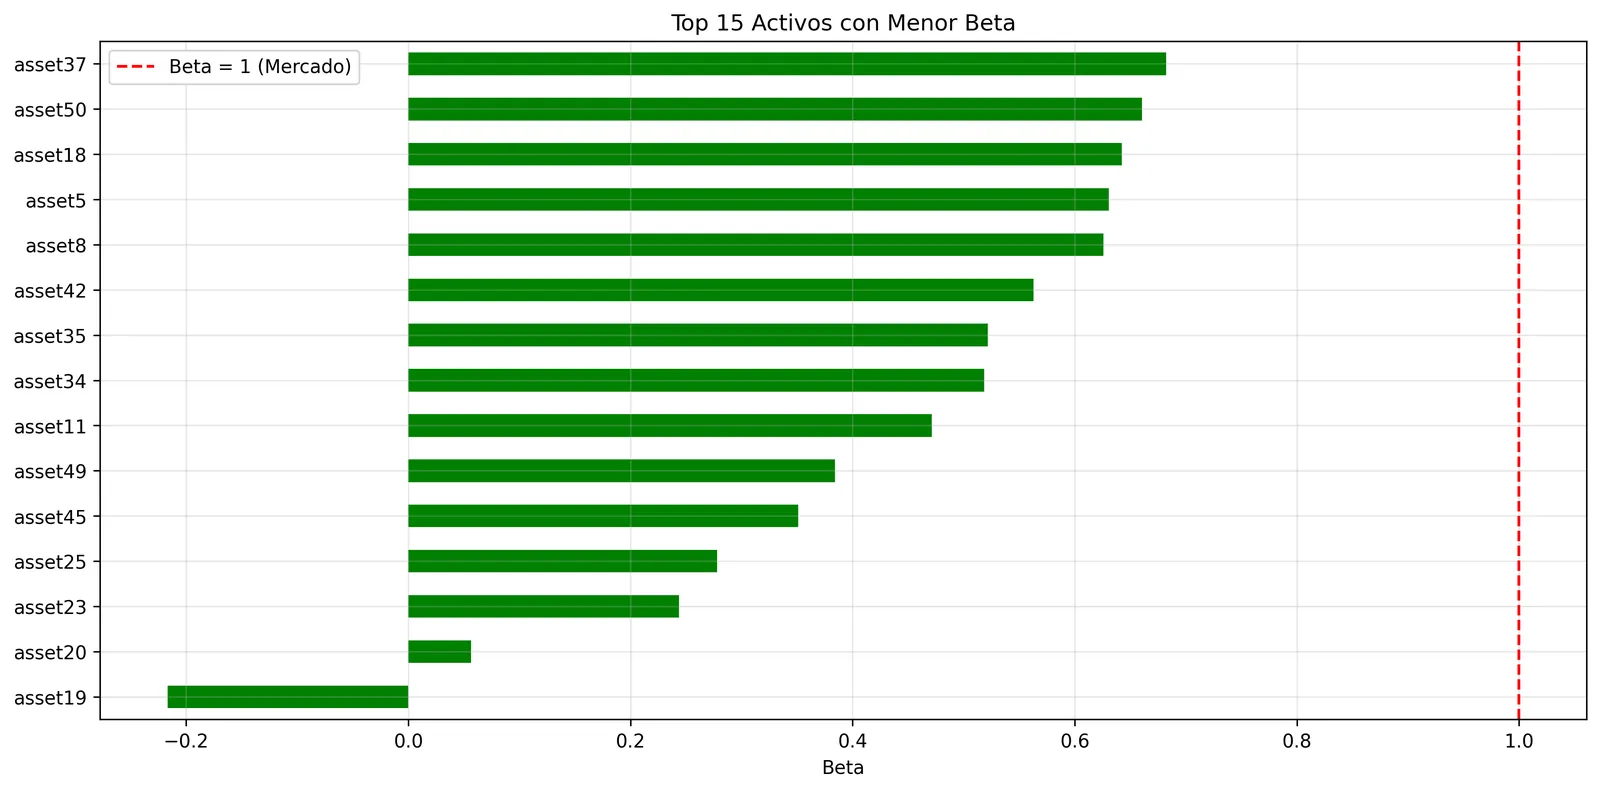
A class competition scored on annualised Sharpe ratio, over 50 anonymised assets and 1,760 days of returns. The code is split into modules: data preparation, equal-weight portfolios and diversification, Markowitz optimisation, asset selection by diversification and Sharpe, a comparison of points along the frontier, and a final check of the constraints before export.
Result
The maximum-Sharpe portfolio reached 1.16 on the training data. That is an in-sample figure, so it says more about the method than about how the portfolio would do next.
Figures