Projects / Master's coursework
Options on SPY
A long straddle, with and without delta hedging
Summary
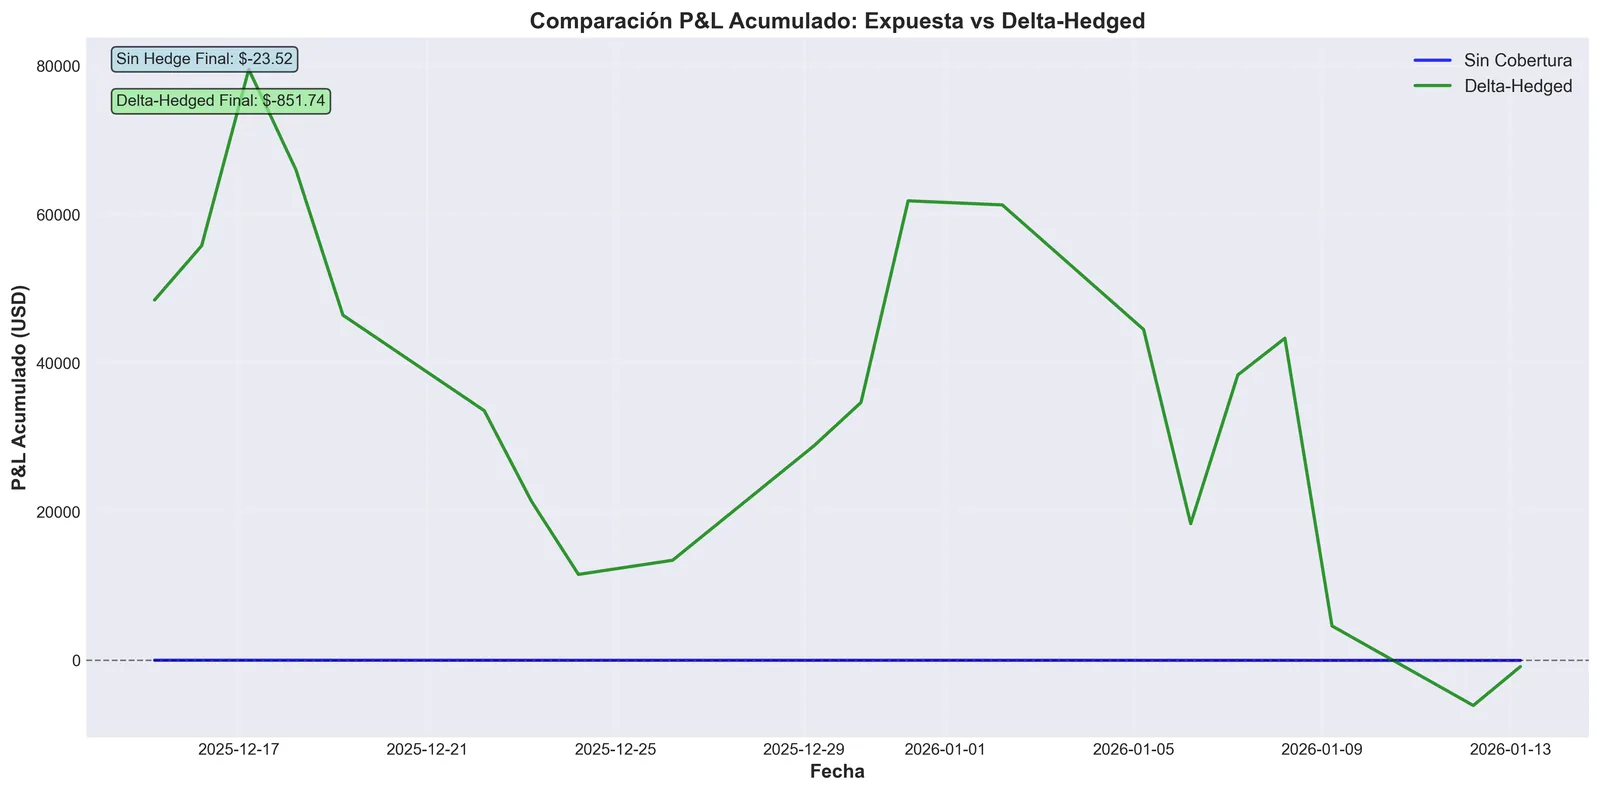
Black-Scholes pricing, Greeks and implied volatility on SPY options, used to build a long straddle and a version hedged every day. The hedge turns the straddle from a bet on direction into a pure bet on volatility. It also compares sending a combo order with legging in.
What it does
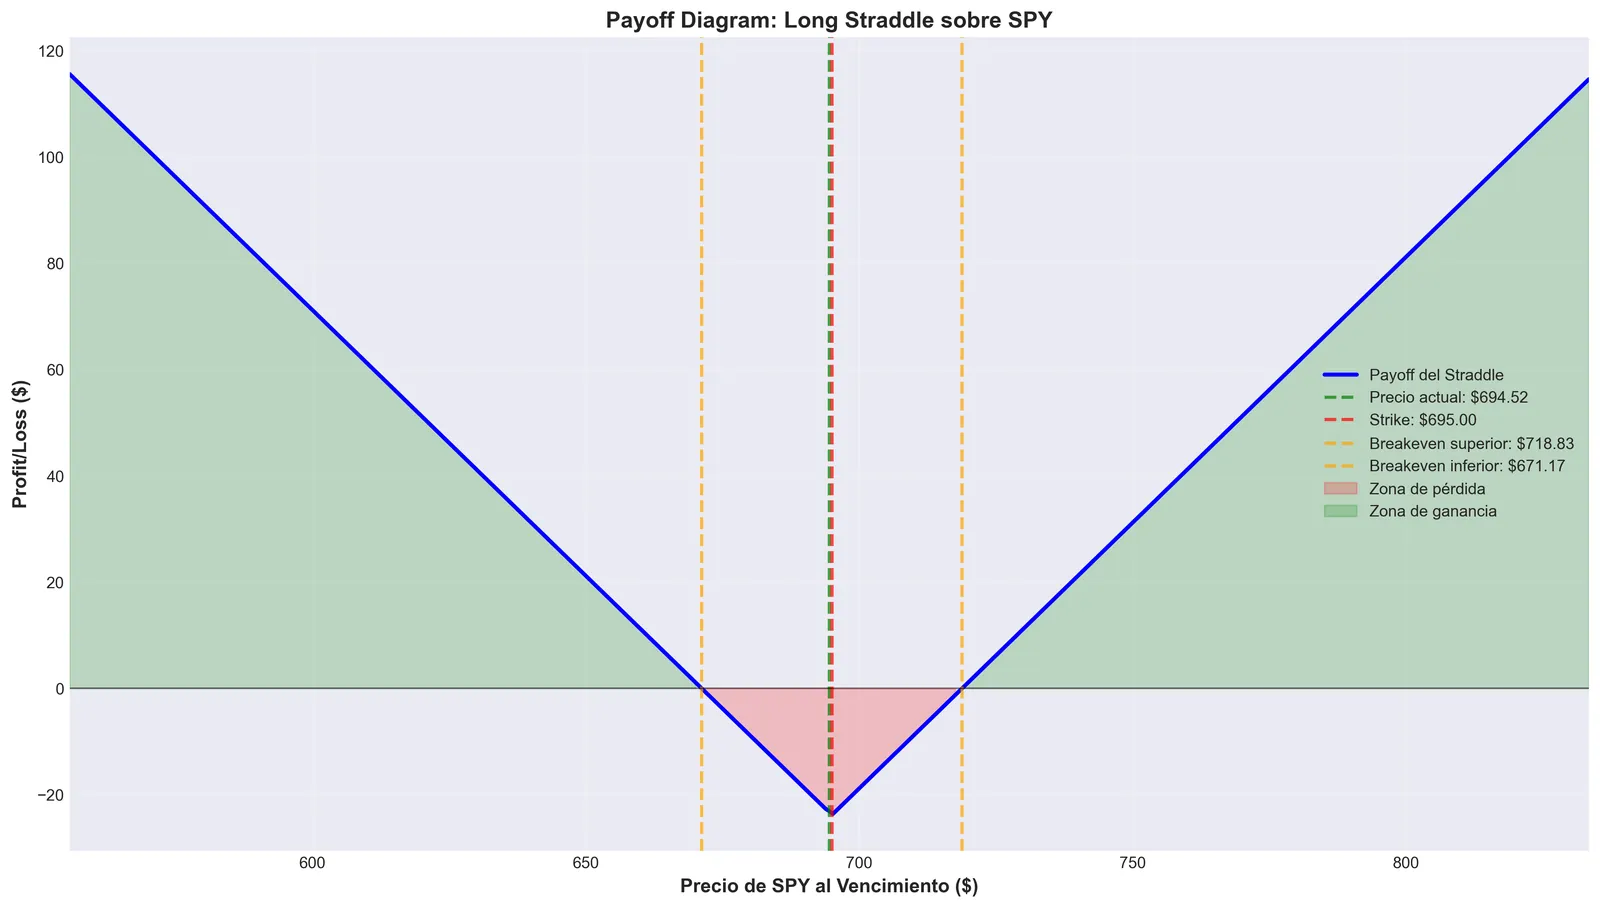
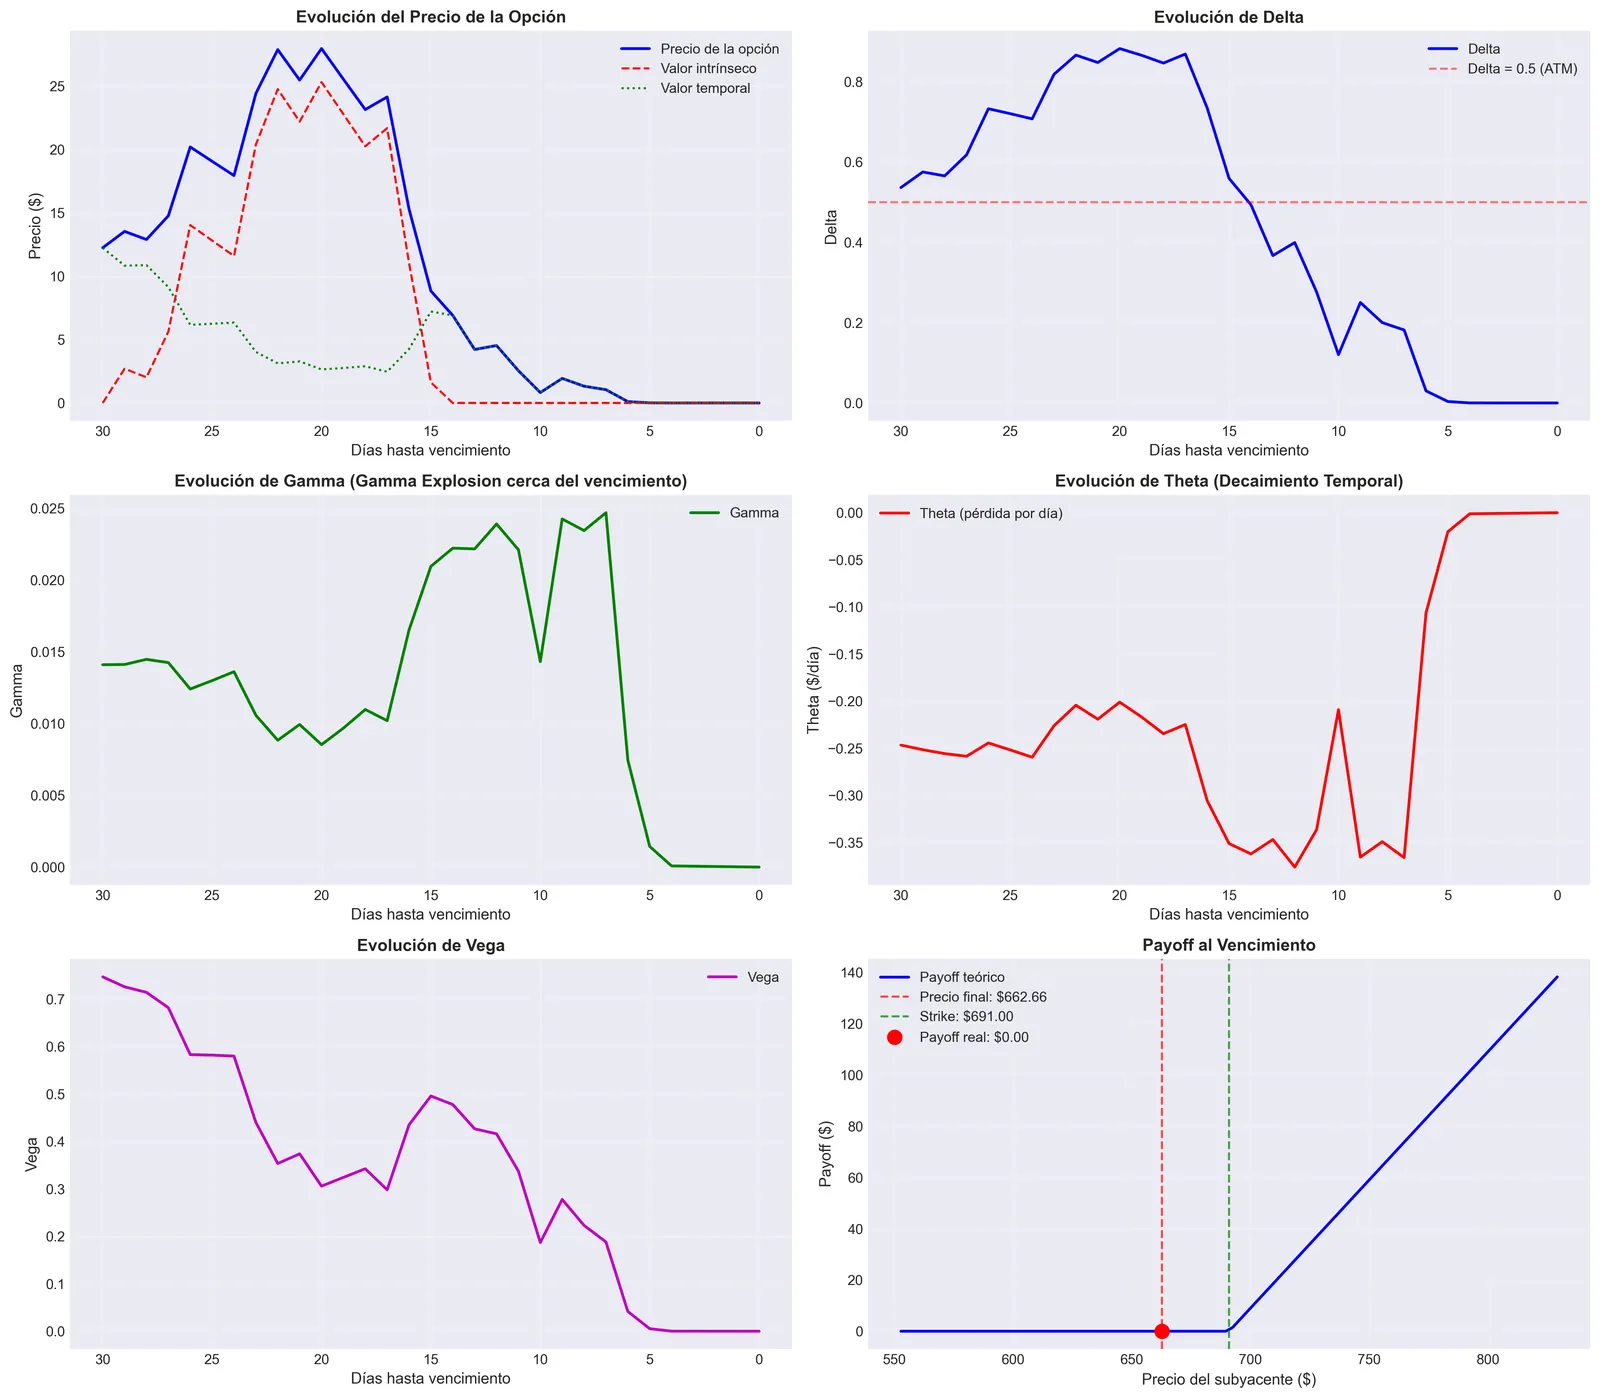
Starting from the course's base code, which connects to Interactive Brokers and prices options with Black-Scholes, Greeks and implied volatility, I built a long straddle on SPY and a version hedged in delta every day. The P&L of both is broken down by Greek, and a simulation compares sending the position as one combo order with legging in one option at a time.
What I learned
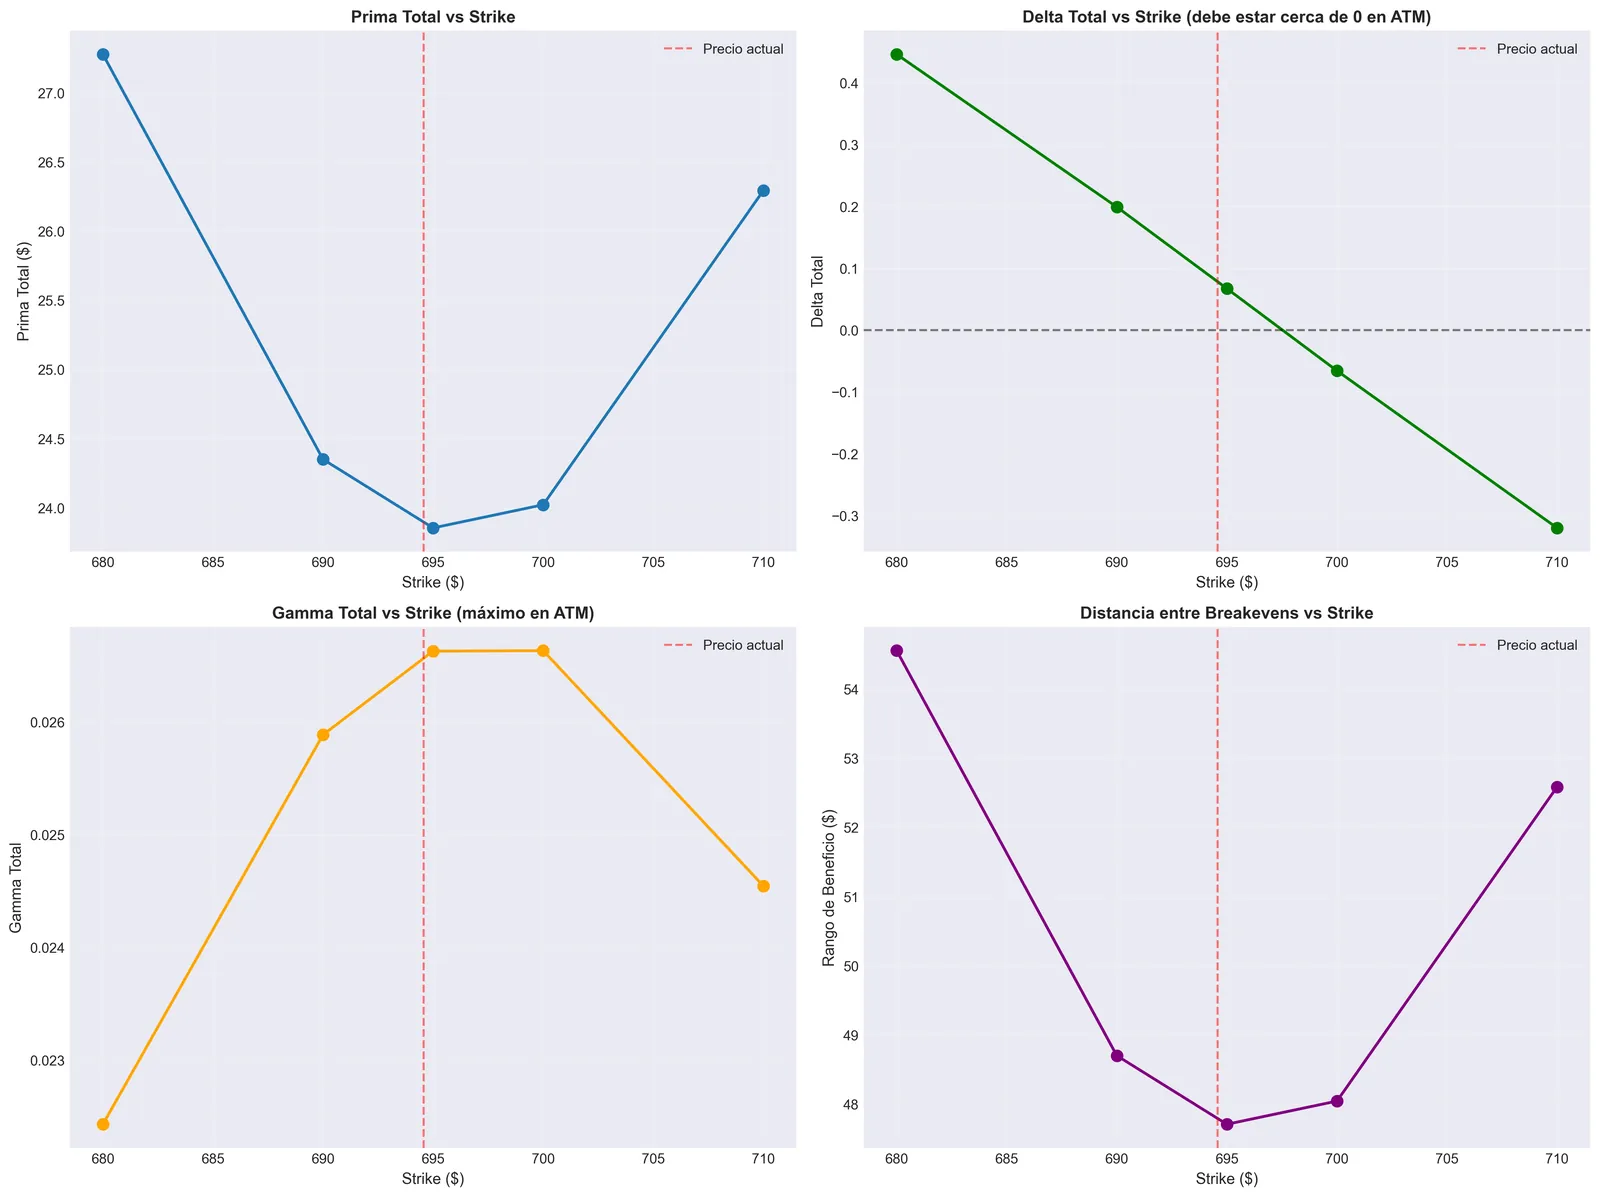
The daily hedge turns the straddle from a bet on direction into a pure bet on volatility, and at-the-money strikes give the best balance between cost and sensitivity.
Figures