Projects / Master's coursework
Fund of funds
A portfolio of funds tilted towards Asia
Summary
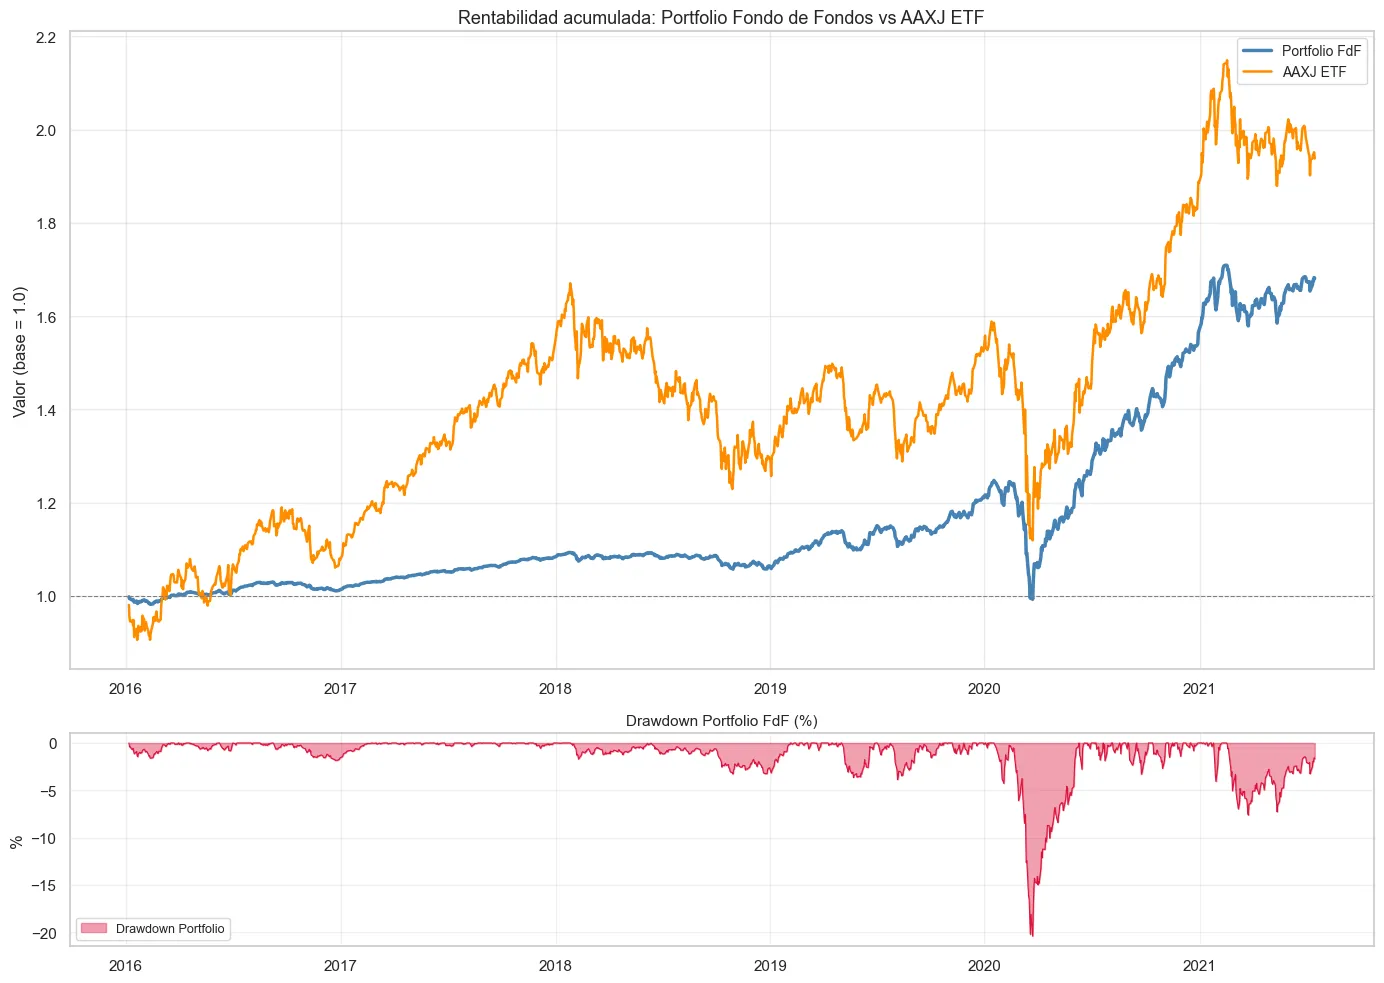
From daily fund prices and Fama-French factors to a portfolio with 70% in Asia, 30% to diversify and no fund above 5%. Funds are grouped by clustering before they are picked, and the result is measured against an Asia ETF.
The thesis
The hypothesis was that Asia would do better than other regions, so the goal was a fund of funds with 70% in Asia, 30% to diversify and no fund above 5%, after minimum quality filters.
How it's built
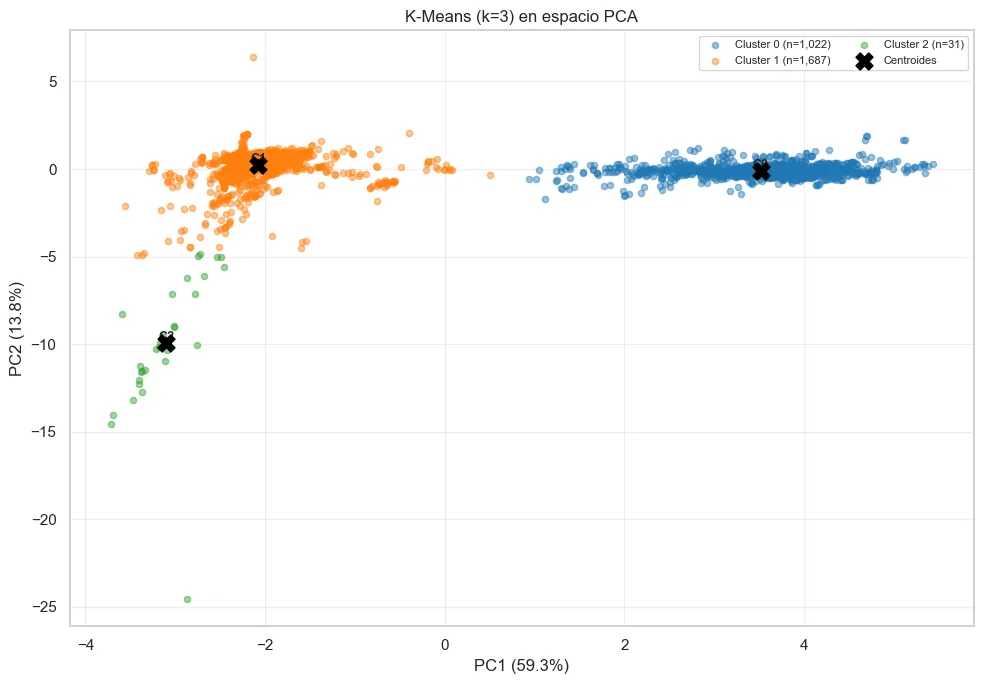
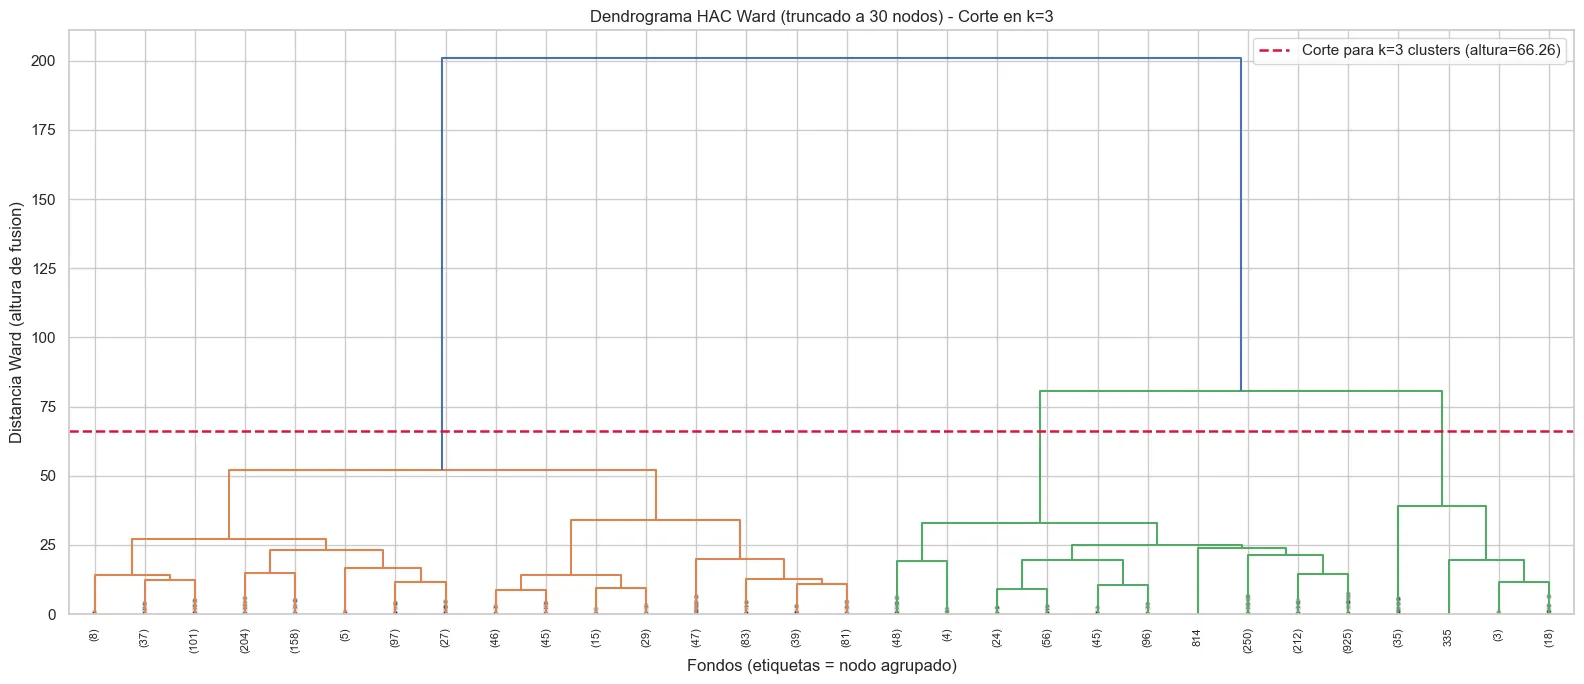
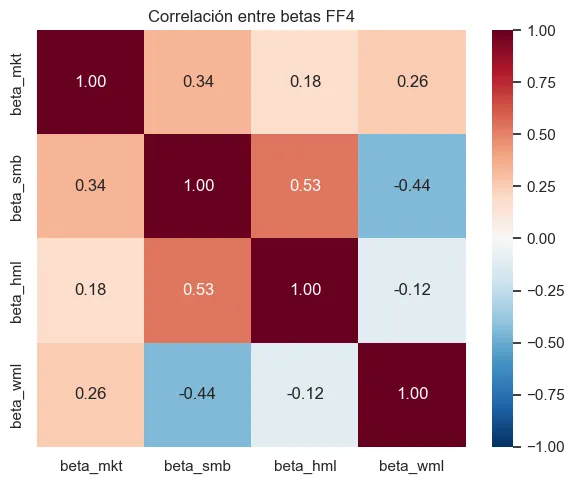
Daily fund prices are merged with Fama-French factors, dates are aligned and the universe goes into one long daily table with quality checks and missing-data handling. Funds are grouped by clustering before they are picked, supervised regression models are fitted on top, and the result is measured against an Asia ETF.
Figures