Projects / Master's coursework
Bond portfolio
Ratings, default risk and concentration
Summary
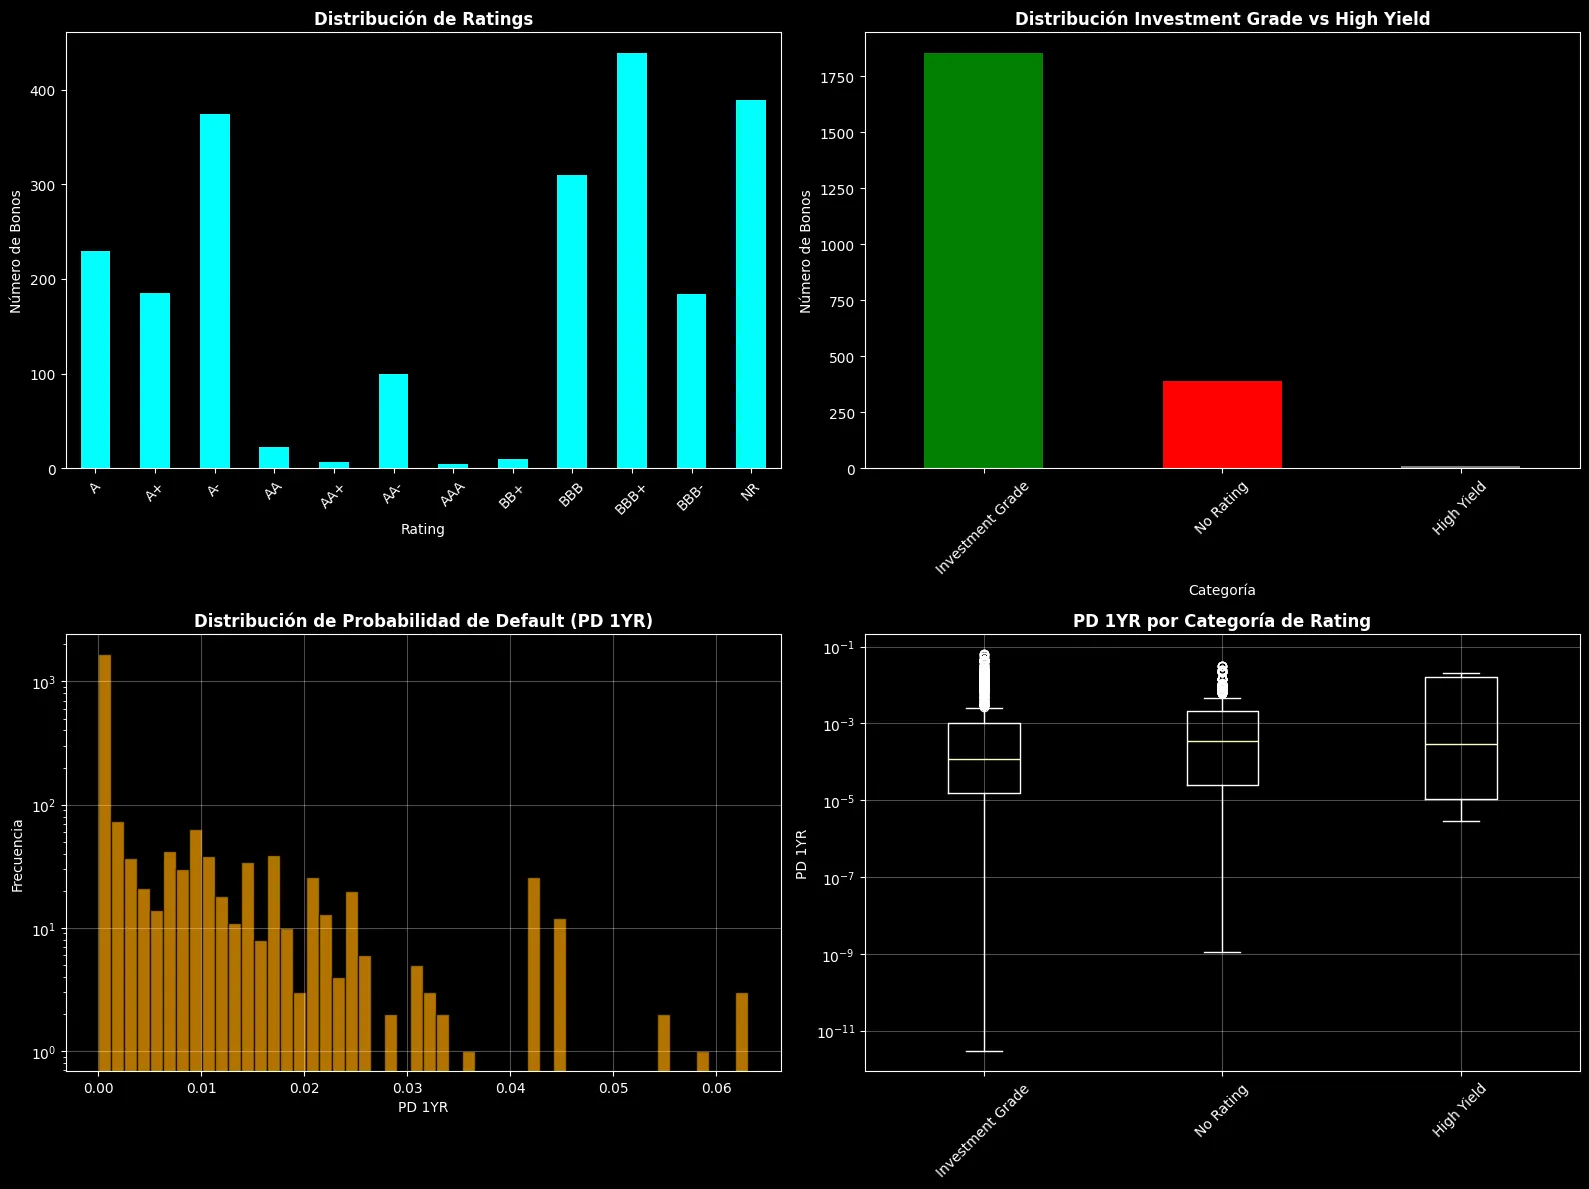
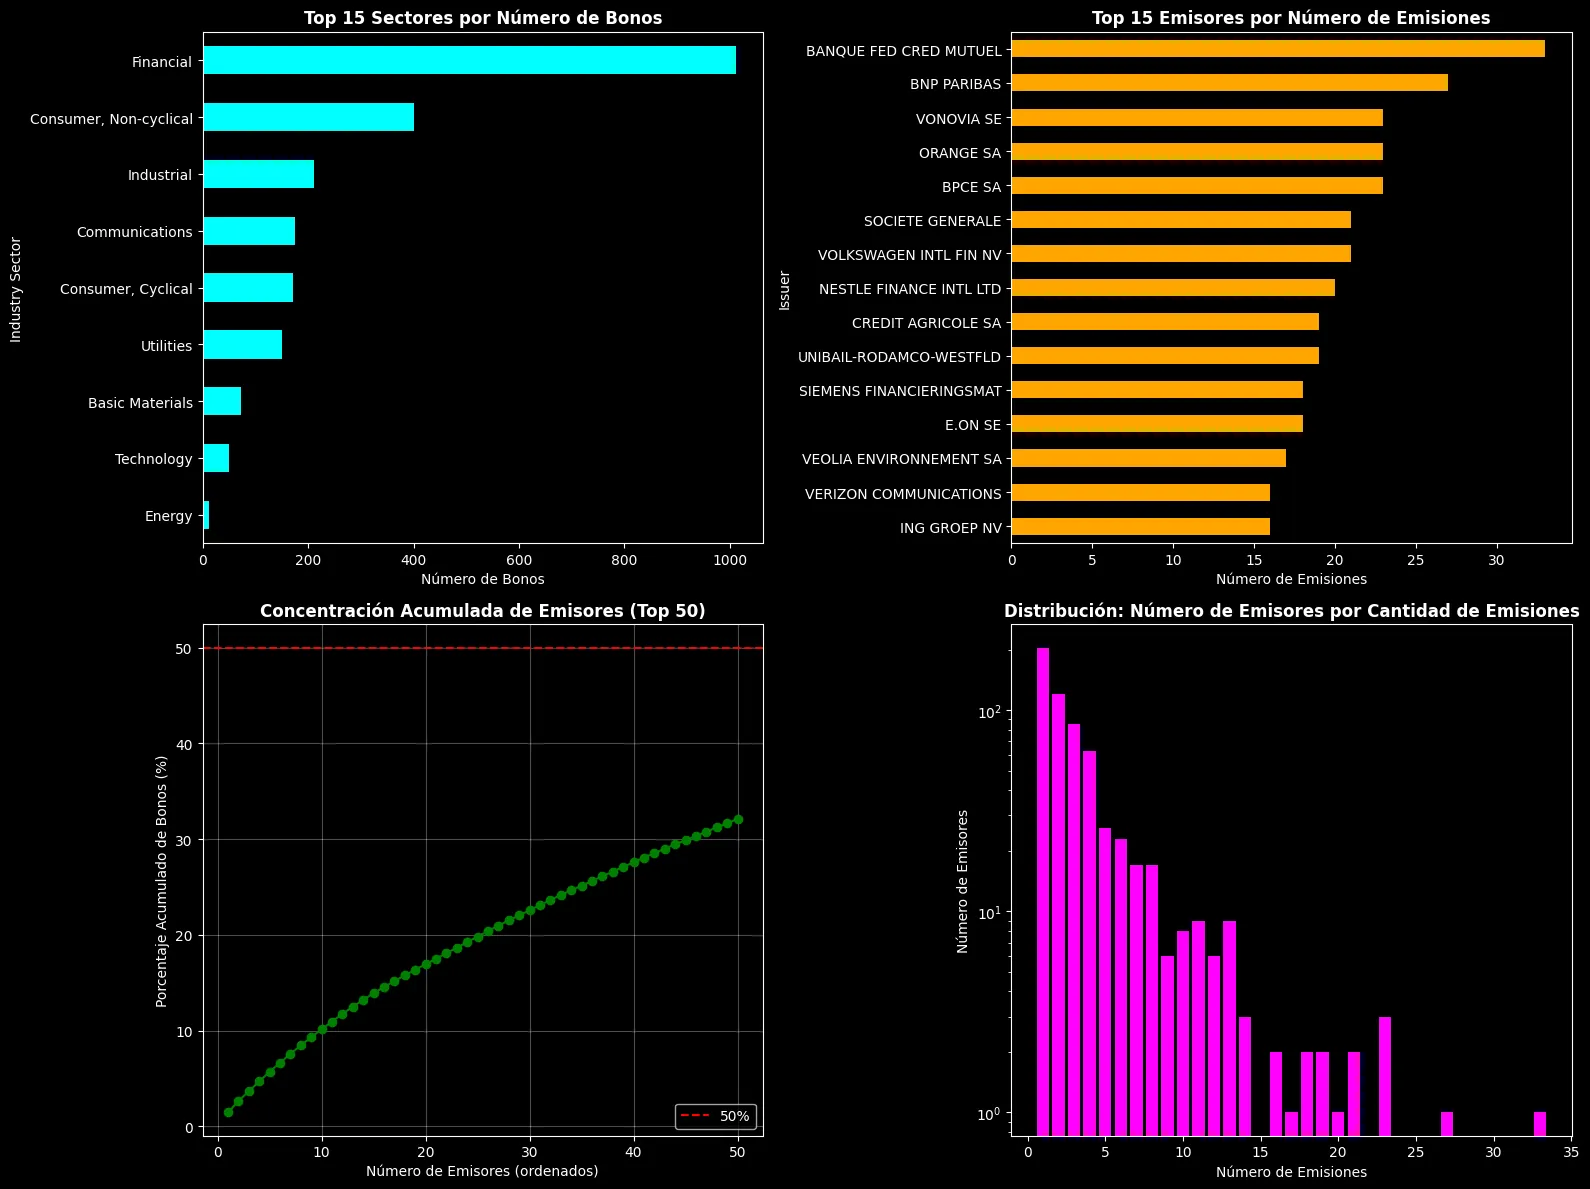
The first fixed-income exercise: reading a bond portfolio by rating, investment grade against high yield, one-year default probability, and how concentrated it is by sector and issuer.
Reading the portfolio
The first fixed-income exercise, on a universe of corporate bonds. First, reading the portfolio: currencies, fixed or floating coupons, seniority, callable and perpetual bonds, ratings with investment grade against high yield, one-year default probability, liquidity through spreads and outstanding amount, and concentration by sector and issuer.
Pricing
Then pricing: each bond valued on the €STR curve plus a credit spread, with clean price, accrued interest and dirty price; the spreads that match market prices; yield, duration and convexity; and an equal-weight portfolio rebalanced every month.
Figures