Projects / Master's coursework
Momentum backtest
The 20 strongest S&P 500 stocks, monthly
Summary
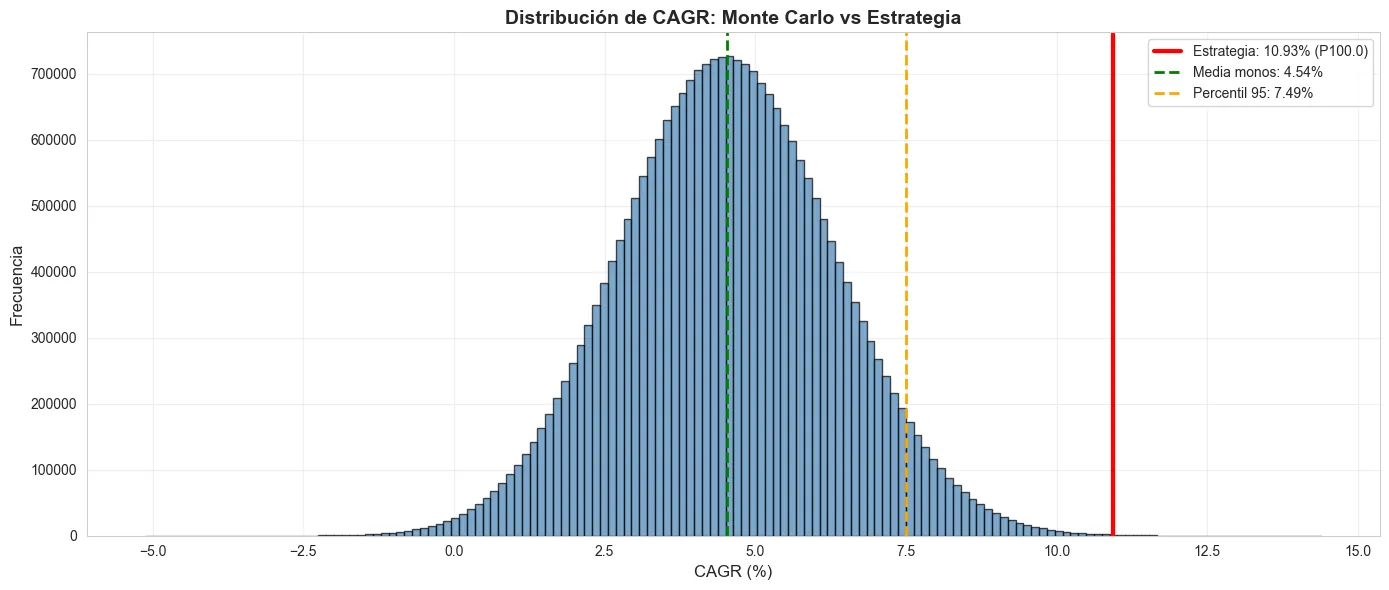
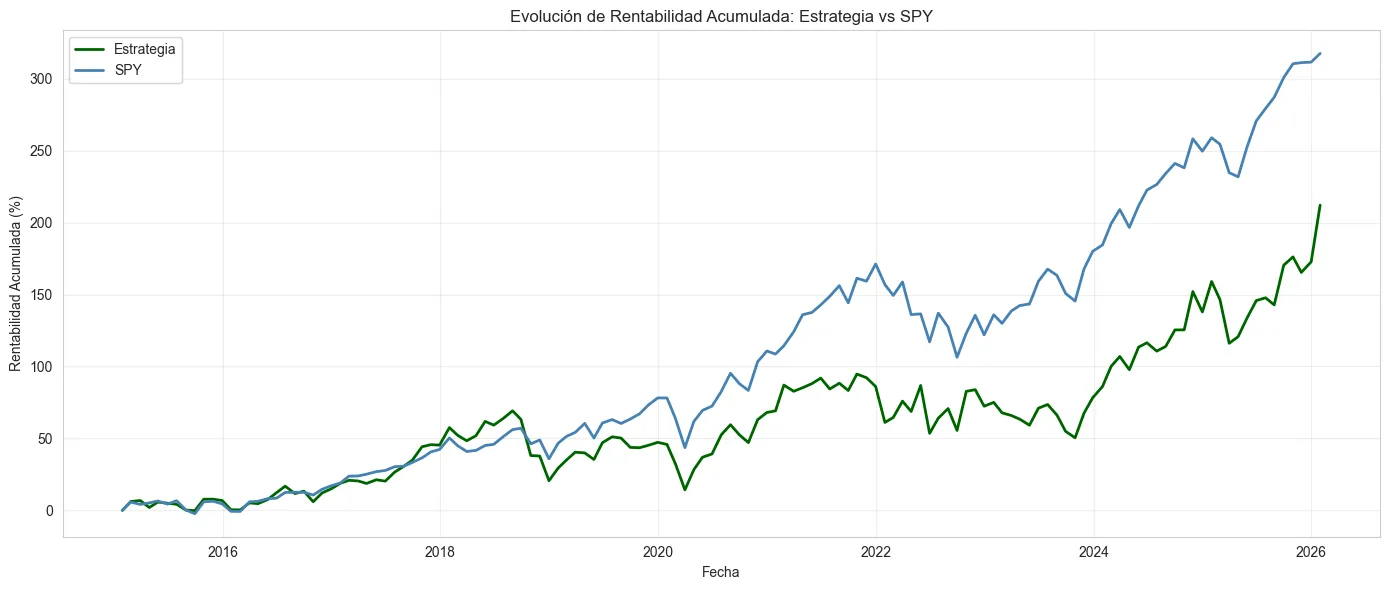
Each month it buys the 20 S&P 500 stocks with the strongest 6- and 12-month momentum, from 2015 on, paying 0.23% per trade and handling stocks that get delisted. Its 10.93% a year beat every one of 25 million random portfolios, which averaged 4.54%.
What it does
A monthly momentum strategy adapted from MSCI's method: each month it buys the 20 S&P 500 stocks with the strongest combined 6- and 12-month momentum, from 2015 on, paying 0.23% per trade. A reserve list handles stocks that stop trading, and prices are kept in a wide dates-by-tickers table so the calculations run vectorised.
Results
It returned 10.93% a year and beat every one of 25 million random portfolios, which averaged 4.54%. The write-up ends with a critical look at what that does and doesn't prove.
Figures