Projects / Master's coursework
Equity arbitrage
Order books from four European venues
Summary
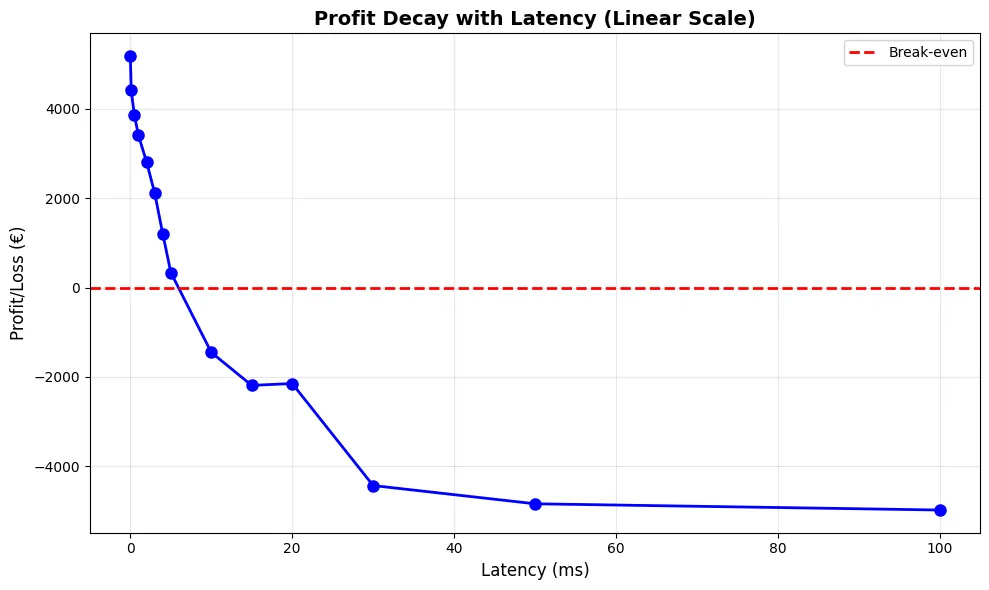
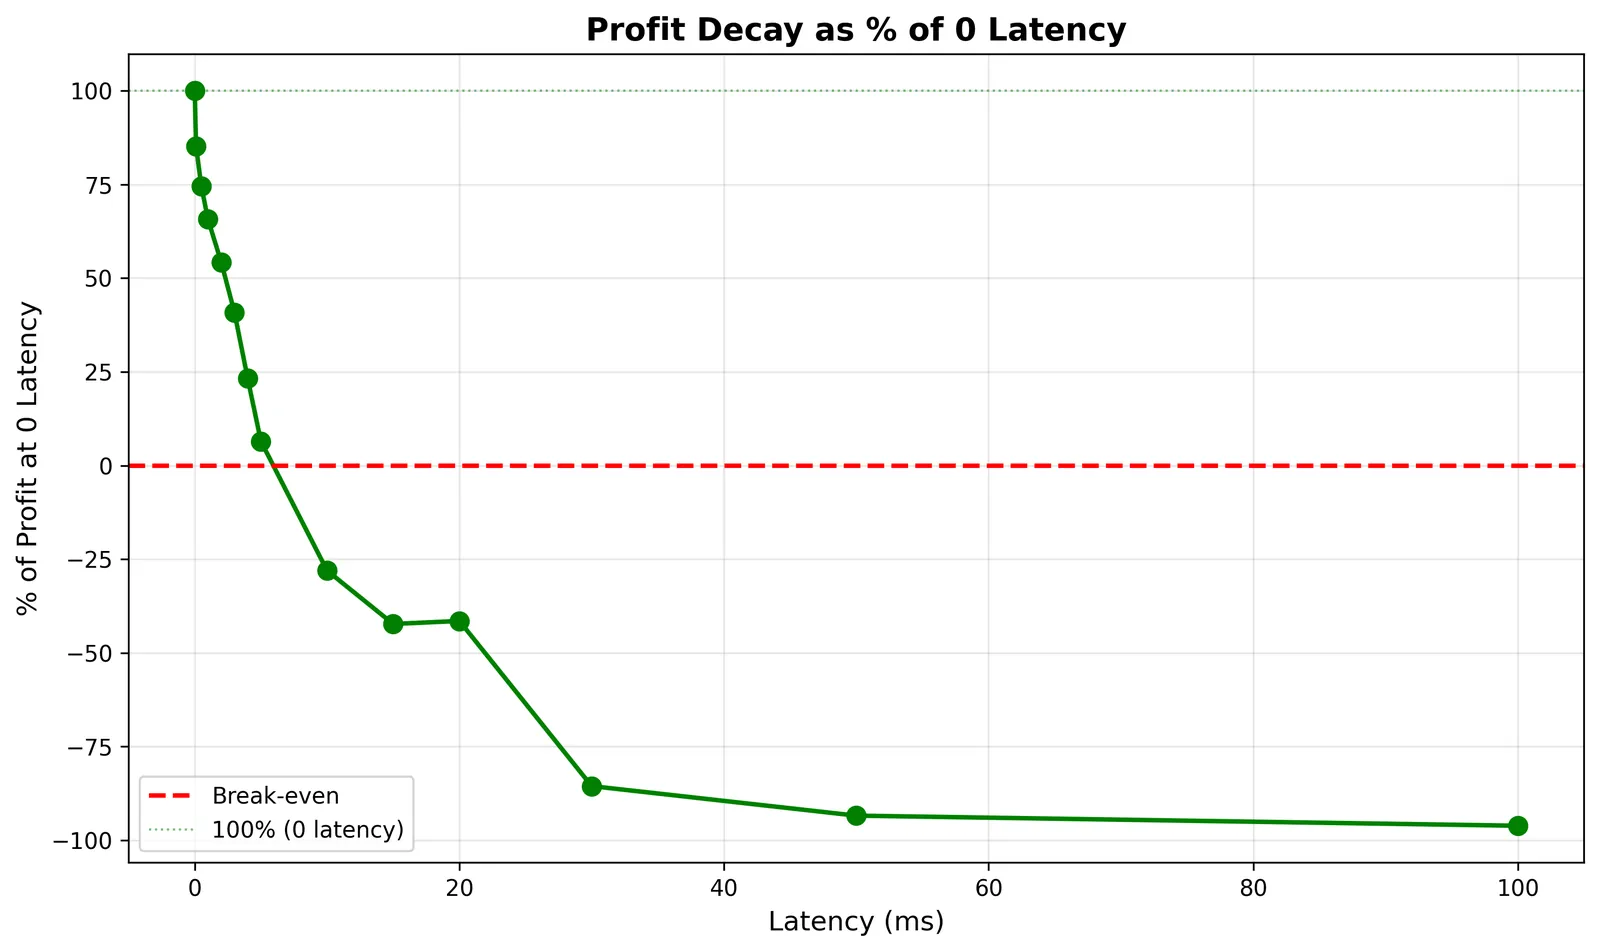
It merges the order books of BME, Aquis, Cboe and Turquoise into one consolidated tape and looks for prices that cross between venues. It found 2,719 opportunities, and showed that a few milliseconds of latency are enough to wipe out the profit.
pandas, with a latency simulator.
What it does
A pipeline over quote and status files from BME, Aquis, Cboe and Turquoise. For each instrument it removes the special placeholder prices venues publish, keeps only continuous trading and merges the four books into one consolidated tape. Then it looks for moments when the best bid on one venue is above the best ask on another, and removes duplicates caused by the same price propagating in time.
Results
It found 2,719 opportunities. A latency simulator then replays each one with delays, and the profit decays fast: a few milliseconds are enough to wipe it out.
Figures